RWA Perpetuals Hit $1.4T: Why Trading Is Exploding
Overview
RWA perpetuals are becoming one of the fastest-growing bridges between traditional markets and crypto-native trading. Recent industry analysis cited by MEXC indicates that onchain RWA perpetual activity in July 2026 reached an annualized trading run rate of approximately $1.4 trillion, reflecting rapid growth in perpetual contracts linked to equities, commodities, foreign exchange, indices and other offchain reference markets.
The number requires an important qualification. $1.4 trillion is an annualized run rate derived from a period of observed trading activity; it does not mean $1.4 trillion of RWA perpetual contracts traded during July, nor does it represent TVL, open interest or tokenized real-world assets held onchain. These products are derivatives that provide price exposure without necessarily giving traders ownership of the underlying stock, commodity or bond.
That distinction helps explain their growth. Tokenizing an actual security can require custody, transfer-agent integration, shareholder rights and jurisdiction-specific regulatory structures. A perpetual contract primarily requires reliable reference pricing, collateral, liquidity and a functioning liquidation engine. Platforms such as Hyperliquid, through its HIP-3 builder-deployed perpetual framework, have significantly lowered the infrastructure barrier to creating new markets.
The result is a parallel path for RWA adoption: legal ownership can move onchain gradually, while economic exposure can move much faster.
Key Takeaways
- Onchain RWA perpetual activity reached an estimated $1.4 trillion annualized run rate based on July trading.
- The number measures annualized trading turnover, not RWA TVL or actual tokenized asset ownership.
- RWA perpetuals provide synthetic exposure to traditional assets without requiring custody of the underlying security.
- Hyperliquid’s HIP-3 framework allows qualified builders to deploy new perpetual markets with their own oracle and contract specifications.
- Derivatives may bring traditional-market risk onchain substantially faster than legal ownership of traditional assets.
What Does $1.4T in RWA Perpetuals Actually Mean?
It Is an Annualized Trading Rate, Not $1.4T of Assets
The first distinction is between trading turnover and asset value. Perpetual markets measure the notional value of contracts traded over time. The same collateral can support many separate transactions as traders open, close and reverse positions, meaning turnover can become much larger than the capital deposited into the venue.
Annualization adds another layer. A period of observed trading activity is extrapolated over a full year to show what volume would look like if the same pace continued. The $1.4 trillion figure therefore describes market velocity rather than an already completed year of trading.
This distinction is essential for interpreting RWA market growth. A trillion-dollar annualized trading rate does not mean a trillion dollars of stocks, commodities or Treasuries have moved onto public blockchains. In many cases, no underlying real-world asset moves at all.
The MEXC On-Chain Daily Report highlighted the $1.4 trillion annualized figure alongside the broader expansion of onchain RWA markets. For longer-term context, MEXC has also tracked Hyperliquid RWA perpetual markets surpassing $500 billion in cumulative trading volume.
Are These $1.4T of Tokenized Real-World Assets?
No. RWA perpetuals and tokenized RWAs solve different problems. A tokenized share or Treasury fund aims to represent ownership, a legal claim or a beneficial interest in an underlying asset. A perpetual derivative can instead reproduce the economic gains and losses associated with that asset without transferring ownership.
If a trader opens a leveraged long position on an equity perpetual, the trader is taking price risk related to the stock but does not automatically become a shareholder. There are generally no voting rights, direct dividends or issuer relationship simply because the perpetual references the company’s share price.
This synthetic structure is precisely why RWA perpetual markets can scale quickly. They avoid many of the operational steps required to move the underlying security itself onto blockchain infrastructure.
Why Are RWA Perpetuals Growing Faster Than Tokenized Assets?
Perpetuals Remove Much of the Issuance Bottleneck
Creating a genuine tokenized public equity can involve securities-law analysis, custody of the underlying shares, shareholder-record infrastructure, restrictions on transfers and a process for dealing with dividends, splits, mergers and voting rights. Even after the asset is issued, the market still needs liquidity and reliable price discovery.
A perpetual contract simplifies the problem dramatically. The venue primarily needs an economically meaningful underlying reference, an oracle methodology, collateral, margin rules and enough liquidity to maintain an orderly market. The product can therefore give traders exposure to an asset long before the legal infrastructure exists to tokenize the asset itself.
This difference helps explain why derivatives have historically scaled quickly in crypto. Traders often care about directional exposure, leverage and liquidity more than physical ownership. If the objective is to trade movements in gold, an equity index or a technology stock, a perpetual contract can satisfy that demand without requiring the exchange to hold the underlying asset for every trader.
The trade-off is that economic exposure and ownership become separated. Perpetuals can democratize access to price risk while offering none of the governance or ownership rights associated with the underlying security.
The Product Fits Crypto-Native Trading Behavior
Perpetual futures are already one of crypto’s dominant trading formats. Traders understand collateral, funding rates and liquidation mechanics, while exchanges and market makers have extensive infrastructure designed around perpetual order books.
Adding traditional-market reference assets therefore requires less behavioral change than introducing an entirely new securities model. A trader familiar with BTC or ETH perpetuals can interact with an equity- or commodity-linked perpetual through essentially the same interface and margin system.
This is an underappreciated advantage. Financial adoption often accelerates when a new asset can enter an existing workflow rather than requiring users to learn an entirely different market structure.
What Markets Can RWA Perpetuals Bring Onchain?
The addressable universe extends well beyond tokenized stocks. RWA perpetual infrastructure can theoretically support any reference asset with a robust price source and sufficient market demand.
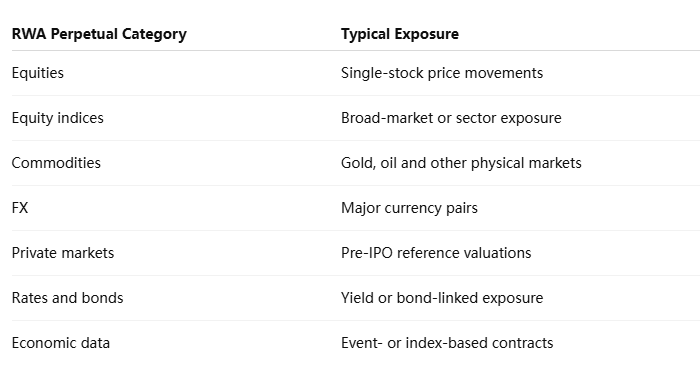
The ease of creating synthetic exposure could expand the number of tradeable markets far beyond what traditional exchanges normally list. Assets with strong economic relevance but difficult custody arrangements are particularly suited to derivative-based access.
However, an asset being technically listable does not mean it creates a sound perpetual market. Reliable external pricing is essential. Thin, infrequently updated or easily manipulated reference assets can create serious problems for margin calculations and liquidations.
That is why market design becomes as important as market creation. The ability to launch a contract quickly must be balanced against whether the underlying reference can support continuous leveraged trading.
Why Does Hyperliquid HIP-3 Matter?
Market Creation Is Becoming More Permissionless
Hyperliquid’sHIP-3 framework allows builders that satisfy the protocol’s requirements to deploy their own perpetual DEX markets rather than waiting for every asset to be listed by a centralized exchange operator. Each builder-deployed market can define contract specifications, oracle methodology, leverage limits and other parameters while using HyperCore’s order-book and margin infrastructure.
That changes the economics of listing. In a traditional exchange model, the venue decides which markets justify integration and operational resources. Under builder-deployed infrastructure, specialized teams can create markets around demand that a general-purpose exchange may consider too small or experimental.
For RWA perpetuals, this can accelerate the development of niche markets. A builder focused on commodities, equities or macroeconomic instruments can develop specialized oracle and market-making infrastructure without needing Hyperliquid itself to centrally operate every contract.
Permissionless market creation does not mean riskless market creation. Hyperliquid explicitly emphasizes oracle quality and requires deployers to consider whether reference prices are economically meaningful and resistant to manipulation. The protocol also uses staking and slashing conditions intended to create accountability for builder-deployed markets.
The Market-Creation Layer Could Become Its Own Competitive Moat
If perpetual infrastructure becomes modular, exchanges may increasingly compete on the quality of builders and markets built on top of them rather than only on centrally selected listings. That resembles how smart-contract platforms grew by allowing developers to create applications without requiring the base network to design each application itself.
For trading, this could generate a much wider long tail of markets. Equities, currencies, commodities and private-company references can be listed according to trader demand rather than according to the timetable of conventional financial infrastructure.
The downside is fragmentation. More markets mean more variation in oracle quality, liquidity and contract design. Traders need to understand not only the underlying asset but also who operates the market and how liquidation and settlement are handled.
Can RWA Perpetuals Trade When Wall Street Is Closed?
24/7 Access Is Valuable, but It Creates a Price-Discovery Problem
One of the strongest attractions of onchain RWA perpetuals is that crypto infrastructure can remain available during weekends and overnight periods when many traditional markets are closed. A trader reacting to geopolitical news on Saturday does not necessarily need to wait until Monday to express a view on oil, equities or macro risk.
That convenience creates a difficult pricing question. When the underlying cash market is closed, there may be no continuously updated authoritative price to anchor the perpetual. The contract instead reflects the expectations of traders active on the crypto venue, along with related instruments that may still be trading.
The resulting price can contain useful information, but it can also become less reliable. Liquidity may be thinner, market makers may demand wider spreads and the perpetual can open a significant basis relative to the next official cash-market price.
This means continuous trading should not automatically be equated with superior price discovery. Onchain markets can provide a live expectation of future prices during off-hours, but the quality of that expectation depends on liquidity and oracle architecture.
RWA Perpetuals vs Tokenized RWAs
Economic Exposure and Ownership Are Two Different Onchain Paths
FeatureRWA PerpetualTokenized RWAUnderlying ownershipNoPotentially yesInstrumentDerivativeTokenized asset or securityExpiryUsually noneNot applicableLeverageCommonUsually spot ownershipVoting rightsNoStructure-dependentDividend rightsReflected indirectly, if at allCan be preserved24/7 tradingPossiblePossibleMain infrastructure needOracle + liquidity + marginLegal + custody + ownershipCore riskLeverage and pricingLegal structure and custody
The distinction helps explain why the two markets can grow simultaneously. Tokenized assets address ownership and settlement. RWA perpetuals address access to risk.
An institutional investor that needs legally recognized ownership of a Treasury fund cannot substitute that requirement with a perpetual contract. A trader who only wants short-term exposure to Treasury yields or an equity index may have little reason to demand direct ownership.
Rather than one model replacing the other, onchain financial markets are likely to develop separate layers for investment ownership and derivatives trading.
What Are the Main Risks?
Leverage remains the most immediate risk. RWA perpetuals allow traders to amplify relatively small movements in traditional assets, and liquidation can occur even when the underlying asset itself remains relatively stable. The combination of crypto-style leverage with traditional-market reference assets can therefore create volatility that does not exist in the cash market.
Oracle design is equally important. A perpetual contract is only as reliable as the pricing mechanism used to calculate marks, funding and liquidations. Market closures, trading halts and illiquid assets make the problem harder.
Regulatory treatment also remains fragmented. A contract referencing a security can attract very different legal considerations from a crypto perpetual, particularly across jurisdictions. Market availability may therefore remain geographically uneven.
Finally, synthetic exposure introduces basis risk. The perpetual price can diverge materially from the underlying reference, especially when traditional markets are closed or liquidity becomes stressed.
MEXC View: Derivatives May Bring TradFi Risk Onchain First
The most important structural insight from the growth of RWA perpetuals is that financial exposure can move faster than financial ownership. Tokenizing a real security requires legal agreements, custody and shareholder infrastructure; creating a derivatives market requires a reliable price and enough liquidity to manage risk.
This asymmetry may shape the next phase of RWA adoption. Traders can gain 24/7 exposure to equities, commodities and macro variables while the underlying assets remain entirely inside traditional financial systems. In effect, the risk moves onchain before the asset does.
For market infrastructure, that creates a different competition from tokenization. The platforms that succeed may be those that deliver the strongest oracle design, liquidity and risk controls across a widening universe of reference markets. The important metric is therefore not only how many RWAs exist onchain, but how much economically meaningful offchain risk can be traded safely through onchain infrastructure.
RWA Perpetuals Show Market Access Can Outrun Tokenization
The estimated $1.4 trillion annualized trading rate for RWA perpetuals illustrates how quickly derivatives can connect traditional-market exposure with crypto-native liquidity. The figure does not mean $1.4 trillion of assets have been tokenized, nor does it represent a completed year of trading. It measures the velocity of an increasingly active derivatives market.
The reason for that acceleration is structural. A perpetual contract can provide exposure without solving the full legal problem of moving the underlying asset onto blockchain rails. That allows equities, commodities, FX and other reference markets to reach crypto traders faster than issuer-sponsored tokenization can reach equivalent scale.
This advantage comes with meaningful risk. Leverage, oracle design, off-hours pricing and regulatory uncertainty become central when contracts trade continuously against assets whose primary markets may be closed. More markets therefore do not automatically produce better markets.
Even so, RWA perpetuals reveal an important direction for onchain finance. The future may develop along two parallel tracks: ownership of real assets gradually becomes tokenized, while synthetic exposure to those assets scales much faster through derivatives. At the moment, the second track is demonstrating how quickly market access can expand when legal ownership is no longer a prerequisite for trading.
Sources
Hyperliquid official HIP-3 documentation:
https://hyperliquid.gitbook.io/hyperliquid-docs/hyperliquid-improvement-proposals-hips/hip-3-builder-deployed-perpetuals
Hyperliquid perpetual market documentation:
https://hyperliquid.gitbook.io/hyperliquid-docs/for-developers/api/info-endpoint/perpetuals
Risk Disclaimer: This article is for reference only and does not constitute investment advice. The cryptocurrency market is highly volatile. Please make decisions cautiously based on your individual circumstances.
You May Also Like
Is Gold Really an Inflation Hedge?
FTIXX Lynq: Goldman's $100B Fund Connects to Crypto Rails